Merlintrader Trading Pub
Biotech catalyst, news and analysis PDUFA tracker
Merlintrader Trading Pub
Biotech catalyst, news and analysis PDUFA tracker
AI transparency: articles and reports are produced with the help of artificial intelligence and checked through a process that does not constitute specialist validation. They may contain errors: verify relevant information with independent sources. Read the full disclaimer.
Cooling the AI Rack: Vertiv, Modine, nVent and Trane Compete Across a Changing Thermal Chain
Compare AI cooling suppliers across air, liquid, racks, CDUs and chillers: installation constraints, service economics and financial exposure.
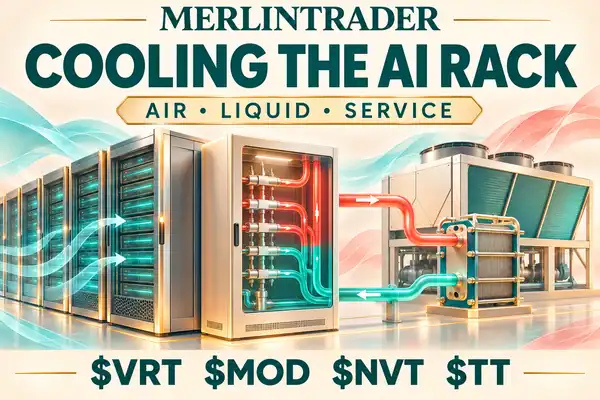
Liquid cooling does not make heat disappear. It moves heat away from electronic components through a different path, and that heat still has to leave the facility or find a useful destination. Between the chip and the outside environment sit cold plates, fluid circuits, coolant distribution units, heat exchangers, chillers, controls and service work. Air cooling can remain part of the same installation.
Vertiv ($VRT), Modine ($MOD), nVent ($NVT) and Trane Technologies ($TT) participate in overlapping parts of this chain. The investment question is more precise than whether artificial intelligence needs more infrastructure. It concerns who supplies each thermal function, how a design becomes an accepted installation, what happens when an existing building is upgraded and which costs stand between orders and shareholder cash.
The latest company disclosures show rapid growth, manufacturing investment and an expanding range of liquid-cooling products. They also reveal different corporate exposures. None of the four companies’ consolidated revenue can automatically be classified as direct-to-chip liquid cooling. Their common opportunity becomes clearer when the equipment, the installation and the financial perimeter are kept distinct.
Extended analysis
Continue with the extended analysis: $VRT $MOD $NVT $TT
The full comparison, company developments, financial context and upcoming milestones.
Free. No signup. You decide, we don’t recommend.
01 — Follow the heat before comparing the stocks
The thermal chain begins with the electronic equipment and ends with heat rejection or recovery. Air can carry heat from components to a room cooling system. Liquid can collect heat closer to a high-output component and transfer it through a circuit. A heat exchanger can separate circuits with different requirements. A chiller can provide refrigeration when the design and operating conditions require it. The final method of releasing heat depends on the facility architecture and local conditions.
The U.S. Department of Energy’s cooling guidance describes both conventional and liquid-cooled arrangements, including the transfer of rack heat through a closed loop and a coolant distribution unit. It also explains the relationship between cooling towers, water use and the facility’s overall heat load. The important distinction is between moving heat within the installation and removing it from the site. DOE cooling-water guidance.
For a supplier, these are different commercial positions. A component manufacturer can sell into a server or rack. A CDU supplier manages the interface between cooling circuits. A plant supplier can deliver larger equipment serving several racks or rooms. Controls coordinate behavior, while maintenance supports the installed system. Some companies cover several positions and compete with partners in selected applications.
This makes “liquid cooling” too broad to serve as a complete revenue category. A new cold plate does not remove the need for every upstream system. A different operating temperature can change the equipment required elsewhere. An integrated supplier can capture more of the chain, while also accepting more responsibility for design compatibility and service. The relevant question is what the company actually sells and supports, rather than how often its presentation mentions AI.
02 — Four companies, overlapping roles
| Company | Relevant thermal exposure | Broader corporate activities | Key financial distinction |
|---|---|---|---|
| Vertiv | Air and liquid thermal management, infrastructure integration and service | Electrical and other critical digital infrastructure | Consolidated growth is broader than cooling alone |
| Modine | Data-center cooling through Airedale and related equipment, including CDUs and plant systems | Commercial HVAC; corporate perimeter changed after the September quarter | Historical totals include a business spun off on October 1 |
| nVent | Liquid cooling, enclosure and rack-related protection and infrastructure | Electrical connection and protection businesses | Data-center exposure includes more than thermal products |
| Trane Technologies | Chillers, controls, service and liquid-cooling equipment | Commercial and residential climate systems and transport refrigeration | Group revenue is not a dedicated AI-cooling measure |
These roles are not exclusive territories. Airedale by Modine markets liquid-to-liquid CDUs for direct-to-chip and hybrid environments. Trane’s September product announcements include a LiquidStack CDU platform as well as a laboratory chiller demonstration. nVent is expanding liquid-cooling manufacturing. Vertiv combines cooling with a wider digital-infrastructure portfolio. A rigid division into one rack supplier and three building-equipment suppliers would misrepresent the overlap. Airedale CDU product description; Trane LiquidStack launch; nVent capacity announcement.
The overlap creates both competition and integration opportunities. A customer may prefer a coordinated system or select equipment from several vendors. The choice affects supplier content, engineering responsibility and the service relationship. A company with products across the chain can offer coordination, while a specialist can compete on a particular function. Neither position guarantees the best margin on every project.
The stockholder owns the whole company, including unrelated markets, financing and capital allocation. Product relevance establishes participation in the opportunity. Segment disclosures and financial statements determine how material that participation is. A technically strong product can be strategically important while remaining a small part of the parent’s current earnings.
03 — Vertiv: strong growth, with a wider denominator
Vertiv reported $4.313 billion of net sales for the quarter ended September 30, 2026, up 61% from the comparable quarter. The release separates 55% organic growth from approximately 6% acquisition contribution. It reports $984 million of operating profit, $1.087 billion of adjusted operating profit and a 25.2% adjusted operating margin. These are consolidated measures across Vertiv’s portfolio. Vertiv October 28 results.
The same release reports $794 million of operating cash flow and $652 million of adjusted free cash flow. It also describes organic orders growth above 100% from the prior-year quarter. These figures demonstrate a strong company-level demand and execution period. They do not establish that thermal equipment alone generated the same growth, margin or cash.
Vertiv’s appeal within the cooling theme comes partly from integration. A customer building a high-density installation needs equipment that works with the rest of its infrastructure and remains serviceable. A supplier with thermal products, engineering capabilities and service can participate beyond a single piece of hardware. The corresponding financial question is how that wider scope converts into profitable, accepted projects without allowing installation complexity or capacity investment to consume the benefit.
The distinction between orders and delivery remains important. A rapidly expanding order book can support future revenue and justify capacity. It can also require materials, labor, engineering and working capital before cash is collected. Growth can therefore increase both the opportunity and the amount of execution the company must deliver. A single strong quarter does not guarantee that the same rate persists.
The company’s September-quarter filing provides the corporate context for these obligations and the mix of products and services. It is the appropriate basis for distinguishing current business from a specific cooling-product narrative. The analytical link is participation across the infrastructure lifecycle; the unsupported leap would be treating all consolidated revenue as a pure liquid-cooling stream. Vertiv Q3 Form 10-Q.
04 — Modine: rapid data-center growth and a changed perimeter
Modine’s latest period is the second quarter of fiscal 2027, ended September 30, 2026. It reported $994.4 million of consolidated net sales and $136.2 million of adjusted EBITDA. The quarter still included Performance Technologies, whose spin-off was completed October 1, immediately after the reporting period. Historical group revenue and the business owned after the separation therefore have different perimeters. Modine November 3 release.
The Data Centers segment reported $439.7 million of sales, up 95%, and a 19.7% gross margin, down 470 basis points from the prior-year quarter. The release attributes the margin decrease primarily to higher material, component and tariff costs. It reports $61.2 million of segment operating income and $67.6 million of segment adjusted EBITDA. Gross margin, operating income and EBITDA are separate measures, with different expenses included.
The figures demonstrate why sales growth and margin expansion are not synonyms. The segment can sell much more and earn more total profit while its gross percentage declines. Production inputs and pricing matter alongside demand. A large market opportunity does not automatically prevent cost pressure during a rapid ramp.
Airedale’s product range also makes Modine broader than a conventional air-cooling category. Its CDU description covers direct-to-chip and hybrid environments, including rear-door heat-exchanger applications. The equipment provides a connection between facility cooling and the technology-side circuit. That position can participate in the transition without assuming that every existing air system becomes obsolete. Airedale CDU range.
For the stock, the next financial comparisons need the correct business perimeter and period. A historical consolidated number that includes a subsequently separated business cannot be used as the unadjusted current denominator. The Data Centers disclosure provides a more direct view of the theme, while the retained commercial HVAC activity and separation-related financial effects remain part of the corporate picture. Modine September-quarter Form 10-Q.
05 — nVent: liquid cooling inside a broader protection business
nVent reported $1.515 billion of sales for the quarter ended September 30, 2026, up 44%, with the same stated organic growth rate. Its release presents results on a continuing-operations basis unless otherwise noted. It reports $282 million of operating income, $335 million of adjusted operating income, $303 million of operating cash flow and $268 million of free cash flow. These are group measures. nVent October 30 results.
The company has liquid-cooling exposure, but also electrical connection, protection, enclosure and other infrastructure activities. Data-center growth can therefore enter through several product categories. A data-center opportunity is not automatically a cooling opportunity, and the entire Systems Protection segment cannot be assumed to represent direct-to-chip equipment.
The July 31 capacity announcement supplies a more specific thermal development. nVent leased an additional 160,000-square-foot site in Blaine, Minnesota, to expand liquid-cooling manufacturing. The company expected production to begin in the first half of 2027. That is a stated future production plan, rather than evidence that the whole site was already shipping at the announcement date. nVent July 31 announcement.
The distinction between space and output matters. A lease creates potential capacity, while equipment installation, staffing, qualification, supply and demand determine usable production. The financial return depends on utilization and margin after the investment. Square footage is evidence of expansion, not a direct conversion into annual revenue.
The October release also says the Maverick Power acquisition closed on October 1, adding a power-distribution platform. That development broadens data-center exposure while reinforcing why thermal and electrical revenue must remain distinct. The acquisition closed after the September quarter; it is not automatically part of that quarter’s historical sales. nVent Q3 release.
06 — Trane: plant expertise now overlaps the CDU layer
Trane Technologies reported $6.760 billion of net revenue for the quarter ended September 30, 2026, with 18% reported growth and 16% organic growth. Its $12.5 billion backlog and approximately $2.8 billion of year-to-date free cash flow describe the broader corporation. The cash figure covers the year to date, not the single quarter, and neither total is a dedicated AI-cooling measure. Trane October 29 results.
The cooling opportunity includes large equipment, controls and service, but Trane’s product range is not confined to the plant room. On September 29 it announced the LiquidStack CDU 2.X platform, described as an architecture-agnostic coolant distribution unit for changing AI infrastructure. The announcement establishes a product launch and its intended role. It does not disclose that all future GPU platforms have selected it. Trane LiquidStack announcement.
A separate September 30 announcement describes a successful laboratory demonstration of an 800-volt direct-current chiller architecture. The demonstrated system delivered more than 3.5 megawatts of cooling capacity, according to the company. A proof of concept is a different milestone from a volume commercial shipment. Cooling capacity is also different from the chiller’s electrical input; the two figures cannot be substituted. Trane laboratory demonstration.
Together, these developments illustrate convergence across the thermal chain. Plant suppliers can move closer to the rack; infrastructure suppliers can broaden the systems they deliver; specialized thermal businesses can add liquid equipment. The competitive map changes as products and acquisitions expand each portfolio.
The stock remains exposure to a broad climate business, including markets beyond data centers. Its installed service relationships and equipment capabilities can be relevant to the theme without making all revenue an AI proxy. The September-quarter filing provides the segment and corporate context needed to retain that distinction. Trane Q3 Form 10-Q.
07 — Air and liquid can coexist in the same building
The transition is not necessarily a choice between an entirely air-cooled building and an entirely liquid-cooled one. A liquid circuit can collect heat from selected components while other components continue to rely on air. A rear-door heat exchanger can capture heat from rack exhaust. Different rooms can use different architectures. The installed base can therefore remain hybrid while high-density workloads expand.
That matters commercially because the transition can create additional integration work rather than a clean replacement of every old product. Existing air-handling equipment may remain useful for residual loads. New liquid equipment may require plant modifications, controls and service. The final design depends on hardware requirements, building conditions and the customer’s operating choices.
The DOE guide describes multiple paths for transferring and rejecting heat. Airedale explicitly markets its CDUs for direct-to-chip and hybrid applications. Those sources support the distinction between adopting liquid at one stage and eliminating air everywhere. Neither establishes a universal percentage of heat captured by liquid for all installations. DOE guidance; Airedale product description.
For suppliers, the opportunity depends on equipment content per installation and the amount of the installed base that needs modification. A hybrid design can preserve some existing demand and add another layer. It can also change the value of particular products. A company that participates in several layers may adapt more readily, while still facing competition and the cost of maintaining a wider portfolio.
The investment distinction is between a structural change in cooling architecture and an assumption that all thermal spending shifts to a single product. The first has strong practical reasons. The second requires evidence about customer designs, selected equipment and purchasing behavior that a broad AI-capital-spending headline cannot provide.
08 — The CDU is an interface, not the final destination of the heat
A coolant distribution unit connects parts of the cooling system while helping manage the conditions of the technology-side circuit. In a liquid-to-liquid arrangement, a heat exchanger separates the circuit serving the equipment from the facility loop. That separation can matter for fluid requirements, operating conditions and control. The unit transfers heat onward; it does not remove the need for the rest of the thermal path.
The Airedale brochure describes the technology cooling system and facility water system as separate loops. Its product information includes controls and service access alongside thermal capacity. The DOE schematic likewise shows the CDU within a larger chain. These are useful references because they explain the role without reducing it to a generic cabinet carrying a large megawatt label. Airedale CDU brochure; DOE guidance.
Capacity ratings need conditions. Thermal performance depends on the temperatures and flows under which equipment is specified. A nominal rating does not establish identical performance in every building or with every server configuration. Comparing two units only by a headline capacity can overlook footprint, service arrangements, controls, redundancy and the requirements of the installation.
The commercial question follows the interface. Who specifies the equipment, who integrates it, who commissions it and who supports it after acceptance? The supplier’s revenue and obligations depend on those answers. A customer buying a unit from one vendor and plant equipment from another still needs the system to work together.
This creates an opportunity for both specialists and integrated suppliers. A specialist can compete on the interface’s performance and flexibility. An integrated supplier can offer coordination across more of the chain. The value of either approach depends on execution and the customer’s priorities. The CDU’s strategic position is real, while its profitability remains a business outcome rather than an automatic consequence of its location.
09 — Water: a closed loop is not a complete water-footprint claim
A closed technology-side loop can circulate fluid without consuming it in the same way as evaporation at a cooling tower. That does not settle the water use of the whole facility. The external heat-rejection method, local climate, operating temperatures and other water needs determine the site outcome. Off-site electricity generation can introduce a further boundary when a broader environmental assessment is made.
DOE guidance distinguishes water and energy performance and explains water use in cooling-tower systems. It describes opportunities such as economizing and improved system operation. The relevant lesson is that a claim about one circuit cannot automatically be extended to all cooling water or the entire energy supply chain. DOE cooling-water efficiency guidance.
The trade-offs can be site-specific. A design that reduces on-site water use can require different equipment or energy under particular weather conditions. A system using evaporation can have a different energy-water balance. Neither architecture can be assigned a universal environmental outcome without defining the location, operating assumptions and measurement boundary.
That boundary also matters for suppliers. A company can provide a component that enables efficient heat transfer without controlling the customer’s complete facility design. Its product claim and the customer’s measured site performance are different evidence. Strong system performance can support demand, but the claim needs to follow the equipment’s actual role.
For investors, water constraints can influence customer architecture, permitting considerations and the value of flexible designs. They do not automatically favor the same supplier in every geography. The useful comparison asks which products can address the customer’s chosen design and whether the company can deliver and support them economically. It avoids treating “liquid” as synonymous with either high water consumption or zero water consumption.
10 — Efficiency: component savings and whole-site economics differ
A more efficient cooling component can reduce the energy used for a defined task. Whole-facility efficiency depends on the complete system and operating conditions. Pumps, fans, refrigeration, control settings and the IT load interact. A percentage improvement in one element is not automatically the same percentage reduction in the data center’s total electricity bill.
Power usage effectiveness, or PUE, compares total facility energy with IT equipment energy over a stated period. It describes overhead relative to the IT load, rather than the useful computing output per unit of energy. A facility can change its workload while its cooling system remains similar. The measurement boundary and utilization therefore matter when interpreting an efficiency claim. DOE definition of PUE.
Trane’s laboratory announcement illustrates the need for boundaries. It concerns an identified direct-current chiller architecture and company-reported test performance. It does not establish the savings of every existing data center or the commercial economics of a future installed fleet. Demonstration, product availability and measured customer performance are separate milestones. Trane September 30 demonstration.
The customer’s economic decision includes purchase price, installation, operating energy, water, maintenance, expected service life and the consequences of downtime. A cheaper unit can become expensive if it requires more integration or performs poorly under the site’s conditions. A higher-priced system can be justified by lower lifecycle cost, but that conclusion requires a specific comparison rather than a generic premium-equipment argument.
For the suppliers, efficiency can support product differentiation and customer demand. Competition determines how much of the value is captured in price, while execution determines the cost of delivering it. An engineering advantage is therefore an input to a margin opportunity, not proof that the company will retain all customer savings as profit.
11 — Retrofit: the existing building changes the project
A new facility can be designed around its intended cooling architecture. An existing building begins with constraints: installed piping, plant capacity, available space, rack arrangement, controls and the need to continue operating. Adding a liquid circuit can require work beyond the server purchase. The economics depend on what can be reused and what must change.
The customer’s tolerance for interruption is especially important. A staged upgrade can preserve operation while spreading deployment over time. It can also increase coordination and engineering work. Equipment that is easy to service or configure may have value beyond its nominal thermal rating. That value remains specific to the project and the customer’s operating requirements.
For a supplier, retrofit can create opportunities in assessment, integration, controls, commissioning and service as well as hardware. It can also create risk if responsibilities are unclear. A component may meet its specification while the overall installation underperforms because of constraints elsewhere. The contract and acceptance criteria determine which party bears the consequences.
This favors a more detailed reading of the four portfolios. Vertiv’s wider infrastructure and service position can be relevant to coordination. Modine’s thermal systems and controls can participate across facility and liquid equipment. nVent’s cooling and infrastructure products can address selected interfaces. Trane’s plant and service presence can matter where existing HVAC systems require modification. These are routes to participation, not predictions that every company wins every retrofit.
The investment question is how much project value becomes revenue, margin and continuing service. A large installed base creates an opportunity set, while customer economics determine the pace of conversion. Announcing a product suitable for retrofit is different from disclosing a funded upgrade order. A forecast that treats all existing racks as immediate replacement demand would skip the customer’s actual decision process.
12 — Manufacturing capacity: floor space is not revenue
Rapid demand can justify more factories, test equipment and supplier commitments. It can also require spending before utilization is certain. nVent’s new-site plan and Modine’s discussion of capacity and supplier arrangements show the industrial work behind the thermal theme. The companies must turn physical space and equipment into repeatable output that customers accept.
The sequence matters. A lease or construction announcement establishes a capacity plan. Installed production equipment brings the site closer to operation. Qualification, staffing and materials determine what it can produce. Orders and delivery schedules determine utilization. Sales recognition and collection complete the financial cycle. Each milestone resolves a different uncertainty.
Costs can rise during the ramp. Materials, components, tariffs, logistics and labor can affect profitability before pricing or productivity catches up. Modine’s Data Centers quarter demonstrates that sharply higher sales can coexist with a lower gross margin. Strong demand does not eliminate the need to manage the cost of growth. Modine Q2 FY2027 release.
Capacity also creates a competitive question. Several suppliers can expand at the same time. If customer architecture changes or deployment slows, planned output may exceed the demand for a particular product. A flexible factory or reusable product platform can help, while carrying its own investment cost. A capacity announcement is therefore both evidence of confidence and a capital-allocation decision.
The return belongs at the corporate level after the investment. More potential megawatts of manufactured equipment do not directly translate into the same amount of profitable installations. Product mix, realized prices, utilization, warranty obligations and working capital determine the economic result. The most informative next update connects capacity with actual production, accepted deliveries and cash.
13 — Orders, backlog and acceptance tell different parts of the story
An order provides evidence that a customer intends to buy within the stated terms. Backlog aggregates work according to a company’s definition. Neither automatically establishes the quarter of delivery or the final margin. Large infrastructure projects can change schedules, specifications and installation readiness. A cooling unit may be complete while the site is not ready to accept it.
The four companies also disclose orders within different portfolios. Vertiv’s consolidated order growth includes its wider infrastructure offering. Trane’s backlog spans broader climate markets. Modine’s Data Centers segment provides a more specific thermal view, while its corporate perimeter has changed. nVent’s infrastructure exposure includes electrical and protection products as well as cooling. Combining those figures into a liquid-cooling market-share table would overstate the data’s specificity.
Acceptance is a separate economic event. The contract may connect payment or revenue recognition with delivery, installation, commissioning or another performance condition. The applicable accounting and contract terms determine the result. An investor cannot infer cash collection simply from a photograph of equipment leaving a factory.
A useful progression follows order quality, scheduled production, customer readiness, acceptance and collection. A delay at one stage can move revenue or cash even while long-term demand remains credible. Repeated delays or cost changes can become a more persistent issue. The distinction is established by evidence over time, rather than by assuming every timing explanation is either harmless or deceptive.
For shareholders, strong orders create visibility and obligations together. They support investment in capacity while increasing the amount the company must deliver. The financial benefit appears when the promised work is executed at an acceptable return. Demand is the beginning of the chain, not its completion.
14 — Service: the installed system can create work beyond the sale
Cooling equipment supports an operating environment whose value depends on availability. Inspection, maintenance, repairs, controls and changes in load can create work after installation. A supplier with an installed relationship may understand the system and respond more efficiently. That can support recurring revenue and customer retention, while also requiring trained personnel, parts and service infrastructure.
The service opportunity differs from a royalty. It is not automatically earned without operating effort. Travel, labor availability, replacement parts and contractual response obligations affect cost. A growing installed base can increase demand while also stretching the organization that supports it. The margin depends on the service arrangement and execution.
Liquid equipment can change the work required. Fluid-related components, monitoring and interfaces add different support needs from a purely air-based installation. Air equipment and plant systems can remain part of the same service relationship. The value lies in maintaining the full required thermal performance, rather than merely selling a recurring inspection label.
For the four companies, service can reinforce a hardware position and provide information about customer requirements. It can also create responsibilities that outlast the original sale. An integrated supplier may capture a wider relationship, while a specialist may support its own component within a multi-vendor system. Clear responsibility matters when an issue spans several pieces of equipment.
The investment distinction is between an installed-base opportunity and guaranteed recurring profit. Evidence of service revenue, margins, attachment and customer retention can support the case where disclosed. A larger installed base alone cannot establish the percentage that will use the manufacturer’s service or the profit earned on each contract. The work remains operational, with real costs and competition.
15 — Financial comparison: growth is broader than liquid cooling
The reported growth rates have different denominators. Vertiv’s consolidated sales include wider infrastructure. Modine’s Data Centers segment is more specific, while its historical group includes the separated business. nVent reports continuing operations across protection and connection. Trane reports a broad climate portfolio. Their percentages cannot be read as four estimates of the same liquid-cooling market.
Margins also need their labels. Modine’s cited 19.7% is a segment gross margin. Vertiv’s 25.2% is consolidated adjusted operating margin. nVent reports operating and adjusted operating measures. Trane provides its own consolidated and segment metrics. A gross margin excludes expenses that an operating margin includes. Ranking these percentages would compare different cost layers before considering product mix.
Cash periods require the same care. Trane’s cited $2.8 billion is year-to-date free cash flow. The cited Vertiv and nVent cash figures refer to their individual quarters. Differences in adjustments and corporate scope add further limits. The figures provide context for their own businesses, while a direct league table would require consistent periods and definitions.
Acquisitions and separations change the perimeter. Vertiv distinguishes organic from acquired growth. Modine completed its spin-off after quarter-end. nVent closed Maverick Power after the quarter. Historical results, current ownership and future guidance can therefore describe different sets of activities. Keeping those dates attached avoids presenting a pro forma assumption as a reported fact.
The meaningful comparison connects the thermal product position with the materiality of the business, its cost structure and its capital requirements. It then considers the stock’s market price and obligations if a valuation is attempted. Product demand alone cannot establish relative investment value, and no undated valuation shortcut resolves the differences in the four corporations.
16 — Working capital and the cost of growing quickly
A manufacturer can spend on components, inventory, labor and factory equipment before collecting from a customer. Strong orders can therefore increase financing needs even when the expected project margin is attractive. Supplier terms, customer deposits and billing milestones influence how much of the growth the company must fund itself.
Inventory can support a planned ramp or protect against supply uncertainty. It can also reflect a delayed installation or a product configuration that customers no longer need in the same quantities. The balance-sheet change needs an operational explanation. More stock is not automatically prudent preparation or a warning sign; the relationship with orders and delivery provides the distinction.
Customer concentration can affect the cycle. A large buyer can bring volume and visibility while influencing prices, specifications and payment terms. Several projects may share the same end customer even if orders arrive through different intermediaries. A growing market does not eliminate bargaining power or the need to manage exposure to a small group of buyers.
The capital-spending decision has a similar timing issue. Capacity built ahead of demand can enable timely delivery and capture growth. If deployment slows, utilization can disappoint. A supplier’s return depends on the timing and flexibility of the investment as well as on the eventual size of the market. The same factory can be strategically useful and financially burdensome during a delayed ramp.
The next financial update can resolve part of this uncertainty by connecting sales, inventories, receivables, capital spending and cash. Strong demand with stable execution and improving collections supports a different interpretation from strong bookings with repeated delivery slippage. Both can begin with an attractive thermal opportunity; their financial outcomes depend on the operating path.
17 — Three scenarios for the competitive map
High-density liquid installations expand quickly. Suppliers can benefit through selected CDUs, thermal equipment and integration. The benefit depends on content and customer selection, while production and working capital must keep pace. A broad portfolio can capture several functions, but also carry more coordination responsibility. Growth in the market does not ensure equal growth for all four companies.
Existing buildings adopt hybrid upgrades gradually. Air equipment can remain useful while liquid capacity is added in stages. Retrofit engineering, controls and service can become important alongside new hardware. The project pace depends on customer economics and operating constraints. A slower transition can change product mix without eliminating the underlying need to remove heat.
Hardware and operating temperatures evolve. Different requirements can change the balance between equipment near the rack and the facility plant. Flexible products may reduce redesign work, while suppliers must continue investing in compatibility and performance. A product announcement establishes intent and availability; installed customer evidence demonstrates adoption.
These are analytical scenarios rather than forecasts. They identify which part of the business changes first: selected content, installation timing or architecture. The financial result then depends on price, cost, capacity and collection. A supplier can gain revenue while margins temporarily compress, or preserve margins while customer deployment shifts to a later period.
The stock comparison therefore remains conditional. Vertiv offers a wider digital-infrastructure relationship; Modine offers a growing thermal business with a changed corporate perimeter; nVent combines liquid cooling with protection and electrical products; Trane combines plant and service expertise with products closer to the rack. Their overlap makes competition relevant, while their differences prevent a single pure-play ranking.
18 — What the next update can demonstrate
For Vertiv, the evidence includes order conversion, product and service mix, capacity execution and cash after growth investment. Consolidated strength is meaningful, while dedicated thermal claims require dedicated disclosure. The next quarter can show whether a strong demand period becomes repeatable operating performance.
For Modine, the retained perimeter and Data Centers segment remain central. Sales, input costs, gross margin, operating profit and capital needs show different aspects of the ramp. Growth in volume can coexist with cost pressure. The financial presentation after the spin-off needs a consistent comparison with the historical period.
For nVent, the thermal capacity plan and the broader infrastructure portfolio need separate tracking. A future site’s production start is different from the announcement of a lease. Maverick Power expands the corporation’s data-center position through electrical distribution, while liquid-cooling output and profitability remain their own operating questions.
For Trane, product adoption, plant equipment, controls and service can reveal where the data-center opportunity becomes material. A laboratory demonstration and a CDU launch are different types of evidence. Neither makes the corporation’s entire backlog or year-to-date cash an AI-cooling measure.
Across all four, the strongest evidence links selected equipment with accepted installations, explained margins and collected cash. Thermal demand establishes the need. Engineering establishes a solution. Manufacturing and service establish delivery. The shareholder result depends on completing that chain at an attractive cost.
19 — Three practical readings of the metrics
Consider an illustrative facility using 100 energy units for IT and 20 for all other functions over the same period. Total energy is 120, giving PUE of 1.20. The additional 20 units are not necessarily all cooling; they include everything inside the facility numerator but outside the IT denominator. Assigning them to one machine would introduce an unsupported assumption. These are mathematical examples, not measured results for the companies or their customers.
If an improvement reduced the additional functions from 20 to 18 with unchanged IT energy, total energy would become 118 and PUE 1.18. The additional functions would improve by 10%, while total energy would fall by two out of 120, approximately 1.67%. Different denominators produce different percentages for the same change. Useful computing output would require another measure if the workload also changed. DOE PUE definition.
A financial example comes from nVent. Its reported quarterly sales of $1.515 billion, operating income of $282 million and adjusted operating income of $335 million imply margins of approximately 18.6% and 22.1%, respectively. The company reports those percentages and provides reconciliations. Both concern the same corporation and quarter, with different expense treatment. Neither is a disclosed margin for a CDU alone. nVent quarterly tables.
Modine’s 19.7% Data Centers gross margin likewise belongs to a different cost layer from its $61.2 million of segment operating income and $67.6 million of adjusted EBITDA. Higher absolute profit can coexist with a lower gross percentage when volume rises and input costs increase. Those observations complement each other rather than creating an inconsistency to remove. Modine segment results.
The third distinction is time. Nine months of cash generation includes more operating periods, collections and investment than one quarter. Dividing the longer figure by three produces an average, not evidence that each quarter generated that amount. Infrastructure deliveries and payments can be uneven. The period remains essential when comparing Trane’s year-to-date cash figure with the quarterly Vertiv and nVent measures.
Water has a separate denominator. Site water usage effectiveness, or WUE, relates water use to IT energy, commonly in liters per kilowatt-hour. It is not another form of PUE. Direct site water and a broader footprint including electricity generation also have different boundaries. A meaningful comparison preserves resource, boundary and period together. DOE PUE and WUE guidance.
20 — Questions that clarify the theme
Does liquid cooling eliminate chillers?
The answer depends on operating temperatures, local conditions and the complete design. Capturing heat near a chip does not remove the need to reject it. Some architectures can reduce refrigeration requirements under suitable conditions, while others still use chillers. The term liquid cooling alone does not specify the plant.
Does a closed loop mean zero water use?
It describes the circuit, not every part of the facility. External heat rejection and the measurement boundary matter. A closed technology loop can coexist with a water-consuming cooling tower elsewhere. A complete claim requires the full site architecture and stated operating conditions.
Can CDU capacity be compared directly with electricity consumption?
Thermal capacity measures heat transferred under specified conditions. Electrical input measures the energy used by the equipment. They are different quantities. A megawatt rating on a cooling product is not automatically its power draw, its annual output or the amount of profitable customer demand.
Which company is a pure AI-cooling business?
The four have broader activities. Even the more direct thermal exposure includes different products and customers. Their corporate financials require segment and perimeter context. A useful comparison identifies material participation without assigning all consolidated revenue to a single theme.
Why can fast growth coincide with lower margins?
Input costs, mix, tariffs, ramp expenses and pricing can change while sales rise. Modine’s latest Data Centers disclosure is a concrete example. Higher total profit and a lower percentage margin can coexist. The source of the change determines whether it reflects timing, investment or a more persistent economic issue.
What is the most useful investment question?
Which thermal function the company supplies, how much value it captures in an accepted installation and what cash remains after production, support and reinvestment. That connects AI demand with the business shareholders own, without treating every equipment announcement as an immediately recurring earnings stream.
Further research and tools
The company research map provides related company coverage. JC Just Charts provides chart tools.
Disclaimer
Educational and informational content, not investment advice or an offer to buy or sell securities. Infrastructure deployment, customer architecture, input costs, competition, supply chains and financing can change. Company guidance and capacity plans are expectations, not guarantees. Figures refer to the stated periods and definitions; scenarios are analytical possibilities. Investments can lose part or all of their value. Merlintrader may hold positions in discussed securities and some site links may be affiliate links. See the full disclaimer and terms and conditions.